Comprehensive Guide to Secure Retirement in Dubai

A New Chapter with Structured Retirement Planning
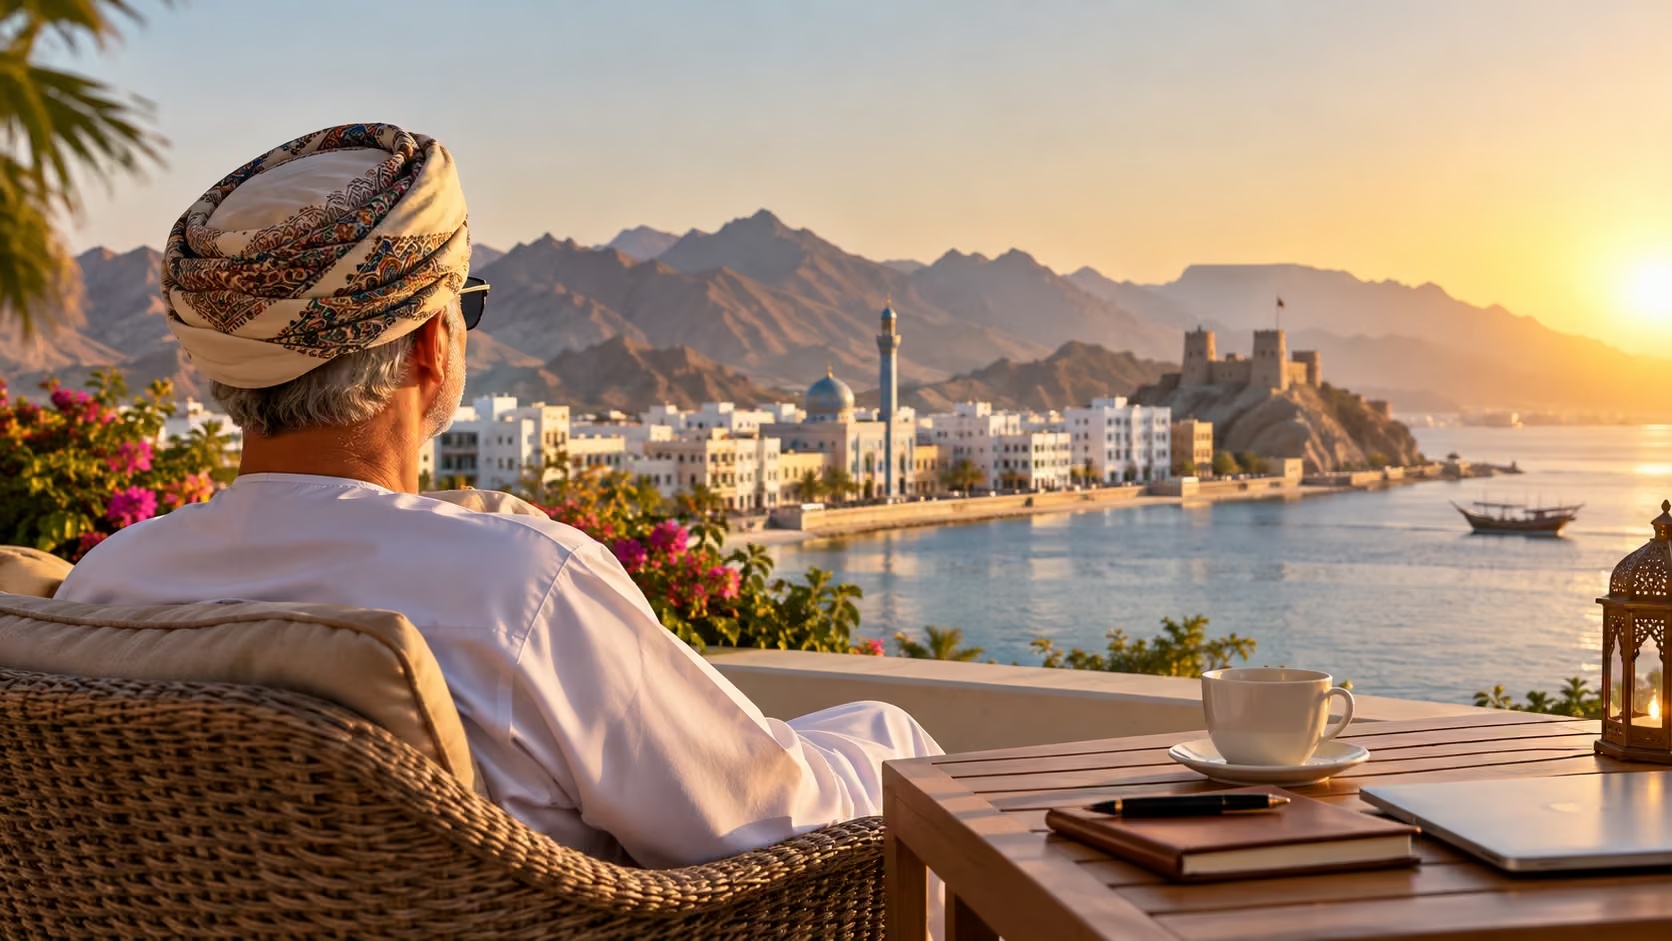
After years of work and saving, many people consider where they want to spend retirement and how their finances would work there. Dubai can appeal to retirees because of its infrastructure, lifestyle, connectivity, healthcare options, and long-term residence pathways, but the financial decision still depends on personal circumstances, costs, residency eligibility, and cross-border obligations.
Dubai offers a residence pathway for eligible foreign retirees. The GDRFA retirement-residence service currently describes a five-year renewable permit and sets age, prior-service, documentation, and financial eligibility conditions. Because immigration requirements can change and the applicable route depends on the applicant’s circumstances, retirees should verify the current official criteria before making financial or relocation commitments.
Retiring in Dubai is not only an immigration decision. Housing, healthcare, insurance, transport, family support, travel, emergency reserves, and portfolio withdrawals all affect the amount of capital required. A useful starting point is to build a realistic spending plan and compare it with expected retirement income and liquid reserves. For local cost considerations, see Cost of Living in Dubai.
A retirement plan should connect spending needs with a suitable mix of cash, income-producing assets, growth assets, and contingency reserves. The objective is not to promise a “safe and profitable” outcome, but to understand which risks the retiree can afford to take, how much liquidity is required, and how withdrawals may affect the portfolio over time. Investment choices should be evaluated individually rather than selected because a market or asset has recently performed well.
The UAE government states that the country does not levy personal income tax on individuals. That does not mean every retiree’s investment income is automatically tax-free: taxes may still arise in another jurisdiction because of citizenship, tax residence, asset location, withholding rules, or estate and succession arrangements. UAE government tax guidance should therefore be considered alongside professional advice on any cross-border obligations.
Retirement in Dubai can be a new chapter, but financial security is never guaranteed by location alone. A stronger plan combines realistic spending assumptions, sufficient liquidity, diversified investments, insurance, and regular review so that the retiree can adapt when markets, health needs, family responsibilities, or regulations change.
How to Plan for Retirement and Tackle the Biggest Concerns
A successful retirement doesn’t happen overnight. It’s the result of years of financial decisions and lifestyle choices. Many people, as they approach retirement, realize they don’t have a clear plan for managing expenses, income, and investments. This is exactly where retirement planning becomes essential.
The first step is understanding your financial needs. You need to know what your retirement expenses will be: housing, healthcare, travel, leisure, and even family support. Estimating these costs accurately helps you understand how much steady income or investment returns you’ll need.
The next major concern is inflation. A retirement plan based only on today’s expenses can underestimate future spending if prices rise over time. Some assets may provide long-term growth or income that helps offset inflation, but no investment reliably “protects” capital in every environment, so inflation risk should be considered together with market risk, liquidity, and the retiree’s withdrawal needs.
The third key factor is risk management. Concentrating retirement capital in highly volatile assets can expose essential spending needs to large drawdowns. At the same time, holding everything in cash can create inflation and longevity risk. The appropriate allocation depends on the retiree’s time horizon, other sources of income, liquidity needs, capacity for loss, and willingness to tolerate market fluctuations.
Rather than starting with a product, begin with the retirement objective and constraints. Cash reserves, bonds, diversified equity exposure, property, or other assets can play different roles, but each introduces its own return, liquidity, currency, credit, concentration, and valuation risks. For a broader decision framework, see Personalizing Your Investment Strategy.
Retirement planning is more than a spreadsheet of numbers. It is a process for translating future spending needs, income sources, risk limits, and personal priorities into a plan that can be reviewed as circumstances change. Starting earlier generally provides more time to save, invest, adjust contributions, and respond to setbacks, but no plan can remove uncertainty completely.
Illustrative Retirement Scenarios: Lessons for Your Financial Future
Illustrative scenarios can help explain why retirement outcomes depend on more than a single investment return. The examples below are hypothetical and are not client testimonials or forecasts. They are designed to show how diversification, liquidity, withdrawal timing, and concentration can affect a retirement plan.
Illustrative Scenario: A More Resilient Retirement
Consider a hypothetical retiree who reaches age 60 with several years of living expenses planned, an emergency reserve, suitable health coverage, and a diversified portfolio rather than a single concentrated investment. Part of the portfolio is intended for near-term withdrawals, while another part remains invested for longer-term growth. The important feature is not a particular product or return; it is the separation of short-term spending needs from capital that can remain invested for longer.
This scenario illustrates why diversification, liquidity planning, and realistic withdrawal assumptions can improve resilience. It does not guarantee that capital will be preserved, because markets, inflation, property values, currencies, and personal expenses can all move in unexpected ways.
Illustrative Scenario: Concentration Risk
Now consider a second hypothetical retiree who places most of the capital needed for future living expenses into one high-risk opportunity because the expected return appears attractive. A severe drawdown shortly after retirement can force withdrawals while the investment is depressed, leaving less capital available to participate in a later recovery. The problem is not simply that the asset fell; it is that concentration and withdrawal timing made the loss harder to absorb.
This scenario highlights sequence-of-returns risk, concentration risk, and the danger of relying on optimistic assumptions for money that may be needed soon. A plan should be tested against adverse outcomes, not only against the expected case.
The Importance of Learning from These Stories
The two scenarios illustrate a broader lesson: retirement planning benefits from clear spending assumptions, diversification, liquidity management, and risk controls. A personalized financial plan can improve preparedness, but it cannot ensure peace of mind, investment gains, or a particular quality of life.
For anyone approaching retirement, the useful question is not which opportunity is “best,” but which combination of assets, cash reserves, insurance, and withdrawal rules fits the household’s goals and constraints. That assessment should also consider cross-border holdings, currencies, family commitments, and the possibility that retirement lasts longer than expected.
How to Build a More Resilient Retirement Plan
Planning for retirement requires foresight, discipline, and a financial structure that can support spending across an uncertain lifespan. The goal is to estimate sustainable withdrawals rather than promise a fixed income stream that will last indefinitely. The plan should reflect lifestyle goals, healthcare needs, existing pensions or business income, investable assets, liabilities, family obligations, and the retiree’s capacity for investment loss.
Understanding Your Retirement Needs
The first step to building a secure retirement is understanding how much money you will need. This depends on factors like your expected lifestyle, healthcare needs, inflation, and longevity. Planning ahead gives you a realistic target to aim for. It’s important to consider both essential expenses (housing, food, medical) and discretionary expenses (travel, hobbies, gifts).
Diversification: The Foundation of a Strong Plan
A retirement plan often uses diversification to reduce dependence on any single asset, issuer, market, or source of return. Diversification can reduce concentration risk, but it does not eliminate losses. Combining different asset classes may help balance liquidity, income, and growth objectives when the allocation is appropriate for the investor.
Depending on the investor, a retirement allocation may consider:
- Equities may support long-term growth, but prices and dividends can fluctuate and losses can be substantial.
- Government bonds and other fixed-income securities may provide income, while still carrying interest-rate, inflation, currency, and issuer-related risks.
- Real estate may provide rental income or capital appreciation, but it is relatively illiquid and can involve financing, maintenance, vacancy, transaction, and concentration risks.
Alternative investments such as gold, commodities, or private-market assets may add different return drivers, but they can also introduce liquidity, valuation, fee, and concentration risks. For more on diversification, see Asset Allocation for a Resilient Investment Portfolio.
The Power of Systematic Investment and Regular Review
Building retirement capital often involves regular saving and investing over many years. Investing on a schedule can reduce reliance on making one large entry decision at exactly the right time, but it does not eliminate market risk or guarantee a profit. Contribution levels and asset allocation should still be reviewed against changing income, goals, valuations, and time horizon.
Retirement planning is not a one-time activity. Life circumstances, spending, market values, interest rates, health needs, and personal goals change, so periodic reviews can be useful. Rebalancing may help restore an intended asset mix after market movements, but changes should be based on the plan rather than on short-term market predictions.
Leveraging Technology and Expert Knowledge
Technology can support retirement planning through budgeting tools, portfolio aggregation, scenario analysis, cash-flow projections, and risk monitoring. These tools can make assumptions easier to test, but they do not make forecasts certain, protect capital, or maximize returns automatically. Human judgment is still needed to interpret results and account for legal, tax, family, and behavioural considerations.
Using Technology in Retirement Planning
Healthcare is an important part of retirement planning. Coverage, exclusions, deductibles, provider networks, long-term care needs, and out-of-pocket expenses can change over time. Building insurance costs and a separate contingency reserve into the retirement budget can improve preparedness for unexpected medical spending, although no reserve can eliminate every healthcare risk.
Tax Efficiency and Estate Planning
Tax and estate planning can be especially important for internationally mobile retirees. The UAE does not currently levy personal income tax on individuals, but foreign-source income, investments, pensions, inheritance, estate rules, or tax-residence status in another jurisdiction may create obligations elsewhere. Estate planning also depends on asset ownership, applicable law, wills, beneficiaries, and succession rules, so cross-border tax and legal questions should be reviewed with appropriately qualified professionals.