How to Invest in the U.S. Stock Market: A Complete Guide to Investing in U.S. Stocks
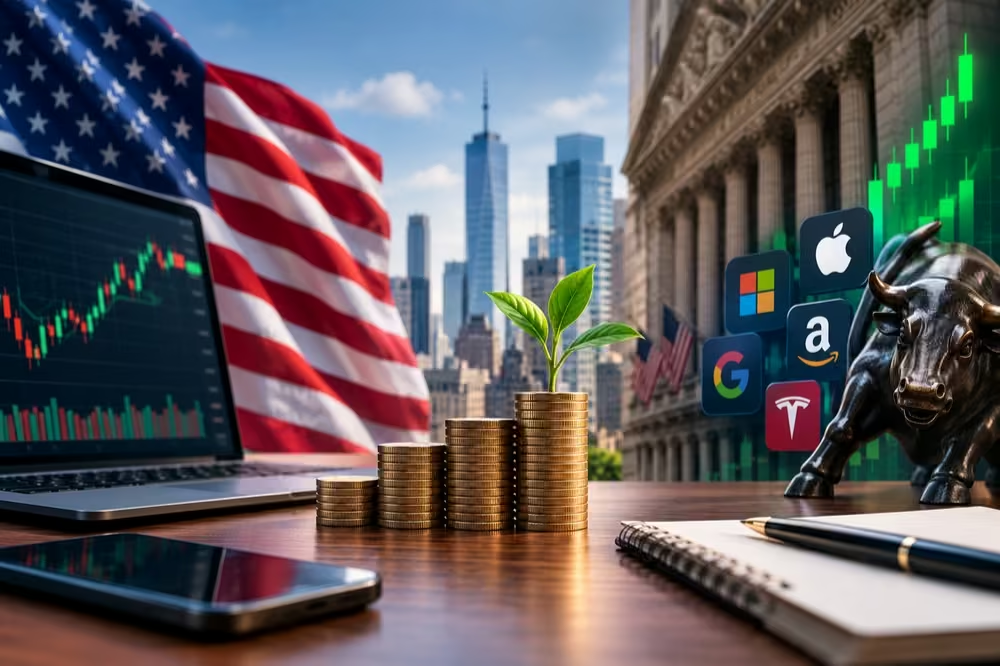
In recent years, investing in international markets has become an increasingly important topic in the Gulf’s financial landscape. As capital markets have developed, asset classes have become more diverse, and economic ties between GCC countries and major global economies have expanded, investors across the region have shown growing interest in markets beyond the Gulf.
Among these markets, the U.S. stock market holds a particularly prominent position. Economic ties between the United States and the Gulf countries have expanded in recent years, while bilateral investments in areas such as technology, energy, infrastructure, and financial services have also increased.
This trend is not limited to government and institutional investments. The development of international investment services and easier access to global markets have also made U.S. stocks and international ETFs increasingly accessible to and relevant for individual investors across the region.
In Oman, interest in international markets can also be seen alongside the development of the domestic capital market. In 2025, the MSX 30 Index recorded significant growth, while funds with a focus on U.S. equities are also available in the Omani market. For example, the United US Markets Fund, regulated by Oman’s Financial Services Authority, invests in a diversified portfolio of U.S. stocks. United Securities: fund details.
In Dubai and other GCC financial centers, access to international markets has likewise become an important part of the investment ecosystem. For example, some international investment platforms provide access to both regional and global markets through a single platform.
But why has the U.S. market attracted so much attention?
The answer goes beyond the names of companies such as Apple, Microsoft, Amazon, Nvidia, or Tesla. The U.S. market offers investors access to a broad range of companies, industries, ETFs, and investment instruments. This diversity can make it one of the markets worth considering when building a diversified international investment portfolio.
However, investing in the U.S. market is not simply about choosing a stock and waiting for its price to rise. Before investing, you need to understand which investment options are available, how to choose an appropriate brokerage platform, how much risk you are willing to take, and which legal and tax requirements need to be considered.
Before Investing in the U.S. Market, Understand These 4 Principles
1. Investing Is Not Only for Wealthy Individuals
You do not necessarily need a large amount of capital to start investing. What matters more is having a clear plan, understanding the risks involved, and choosing investment instruments that match your financial circumstances.
The amount of capital you have, your financial objectives, and your investment horizon all help determine which types of assets may be appropriate for your portfolio.
2. The Stock Market Is Not a Shortcut to Overnight Wealth
The U.S. market offers many opportunities, but no individual stock or fund can guarantee a profit.
Successful investing generally depends more on time, discipline, diversification, and risk management than on finding a “magic stock.”
3. Investing Requires Knowledge and Expertise
Understanding financial statements, valuation, market indices, investment funds, and market risks can help investors make more informed decisions.
If you do not have enough time or knowledge to manage a portfolio directly, working with a qualified financial advisor or investment manager can also be an option to consider.
4. There Is No One-Size-Fits-All Investment Strategy
An investor with a 15-year investment horizon may be comfortable taking on more risk, while someone who expects to need their capital within the next few years may require a different asset mix.
Therefore, the right question is not always:
“What is the best investment?”
A more important question is:
“Which type of investment is appropriate for my financial goals, investment horizon, and risk tolerance?”
Why Can the U.S. Stock Market Be Part of an Investment Portfolio?
Investing in the U.S. market is not limited to buying shares of a few well-known companies. The market provides access to a broad range of stocks, ETFs, securities, and industries.
This diversity has made the U.S. market an option that many investors consider alongside their domestic markets as part of an international investment portfolio.
Access to Major Companies and Global Industries
One of the key characteristics of the U.S. market is the presence of companies operating across a wide range of industries, from technology and artificial intelligence to healthcare, energy, consumer goods, and financial services.
This allows investors to build a more diversified portfolio rather than concentrating their capital in a single company or industry.
For example, a portfolio could include a combination of large-cap stocks, index-based ETFs, and other assets, with the specific allocation determined by the investor’s objectives and risk tolerance.
Diversifying an Investment Portfolio
One of the fundamental principles of wealth management is avoiding excessive dependence on a single market or asset class.
If a large portion of an individual’s wealth is concentrated in one type of asset, such as real estate, bank deposits, or a particular market, the overall performance of their wealth can become heavily dependent on the conditions of that market.
The U.S. stock market can be one way to add both geographic and sector diversification to an investment portfolio.
However, diversification does not eliminate risk. Even a diversified portfolio of U.S. stocks can decline in value during periods of market downturns. U.S. SEC: diversification.
Investing With a Long-Term Perspective
The stock market is generally more suitable for investors with a long-term investment horizon who can tolerate short-term fluctuations.
With this approach, the goal is not simply to trade stocks frequently. Instead, investors seek to select assets that align with their long-term financial objectives and then regularly review and manage the portfolio as conditions change over time.
Does Investing in the U.S. Market Mean Buying Shares of American Companies?
Not necessarily.
One important feature of the U.S. market is that many of the investment instruments traded there can provide exposure to companies and industries around the world.
For example, ETFs can give investors exposure to a group of companies within a particular industry, index, or geographic region rather than requiring them to invest in a single company.
Therefore, the choice between individual stocks, ETFs, and other investment instruments should be based on the investor’s objectives, risk tolerance, and investment horizon.
How Can You Invest in the U.S. Stock Market?
There is no single way to enter the U.S. stock market. The right approach depends on the type of investment you are considering and the services you choose.
1. Using an International Brokerage
One of the most common approaches is to open an account with a brokerage firm that provides services to international clients.
During the account-opening process, the brokerage will typically review your identity, country of residence, financial information, and the documents required to meet Know Your Customer (KYC) and Anti-Money Laundering (AML) requirements.
An important point to remember is that not every brokerage provides services in every country. Before opening an account, you should confirm that the brokerage currently accepts clients residing in Oman and understand its requirements for opening and maintaining an account.
2. Investing Through Investment Firms and Wealth Managers
If the goal is to build a professionally managed portfolio, investors can consider working with wealth management firms or investment advisors.
Instead of making every buying and selling decision yourself, your financial circumstances, objectives, and risk tolerance are assessed first. An investment strategy can then be developed based on those factors.
This approach may be particularly relevant for investors who do not have the time or expertise to manage their investments on a day-to-day basis.
3. Investing in ETFs and Index Funds
Investing in the U.S. market does not necessarily mean choosing individual stocks.
For example, the S&P 500 is an index, not a stock that you can purchase directly. However, there are ETFs and funds designed to track the performance of the index. U.S. SEC: ETFs.
These instruments can provide exposure to a group of companies and may offer greater diversification than investing in a single stock.
However, diversification does not mean an ETF is risk-free. Equity ETFs can also decline in value when the market falls.
4. Using Derivatives and CFDs
Another method investors may encounter on trading platforms is trading Contracts for Difference (CFDs).
With a CFD, you generally do not own the underlying stock or index. Instead, you trade based on changes in the asset’s price. Some CFD transactions also involve leverage.
For example, if a trade is conducted with 10x leverage, price movements can have a much larger impact on the capital allocated to the trade. This also means that losses can increase rapidly. UK FCA: CFD risks.
For this reason, CFDs and leveraged trading should not be treated as equivalent to long-term investing in stocks or ETFs.
Investing and trading are two different strategies. Before choosing either approach, you should understand exactly what you are buying, what risks you are taking, and under what circumstances you could lose your capital.
Before Investing in the U.S. Market, Don’t Overlook Taxes and Regulations
International investing is about more than choosing a stock or ETF. Once you invest your capital in another market, you need to consider not only market risk but also regulatory requirements, identity verification, and potential tax implications.
When opening an account with an international brokerage, your identity and country of residence will generally be verified, and you may be required to provide documents confirming your identity and financial status.
The type of asset you invest in and your tax residency may also affect how taxes are calculated or withheld.
Taxes on Investment Gains and Income
Capital gains from an increase in a stock’s price, dividends, interest, and other forms of investment income are not necessarily treated the same way for tax purposes.
For example, investments in U.S. securities may be subject to U.S. tax rules applicable to nonresident investors. The type of income, residency status, and investment structure can all affect the final tax treatment. IRS: nonresident tax rules.
At the same time, the tax rules of the investor’s country of residence should be considered separately.
For this reason, you should not make tax decisions based solely on another investor’s experience.
What Should You Check Before Transferring Your Capital?
Before opening an account and transferring funds, it is worth clarifying the following:
- In which jurisdictions is the brokerage licensed to operate?
- Does it accept clients residing in Oman?
- What documents are required for identity verification?
- What are the trading, account maintenance, and other applicable fees?
- How are your assets held and safeguarded?
- How are dividends and other investment income paid?
- What taxes may apply in the source country or the investor’s country of residence? U.S. SEC: BrokerCheck.
- What investor-protection mechanisms are available if a problem arises?
These checks may not be as exciting as choosing a stock, but they can help prevent costly decisions later.
International investing is generally more effective when an investor understands not only what they are buying, but also how their capital enters the market, which rules apply, and what costs are involved.
How Do You Choose the Right Stocks in the U.S. Market?
One of the first questions that comes up after becoming familiar with the U.S. stock market is:
Which stocks are worth considering?
The answer is not the same for everyone. A company that may appeal to an investor with a long-term horizon and a higher risk tolerance may not be appropriate for someone seeking lower volatility and greater capital preservation.
Instead of searching for the “best stock,” it can be more useful to evaluate companies based on a range of characteristics.
Growth Stocks
Growth stocks generally refer to companies that the market expects to increase their revenue or earnings at a relatively high rate in the future.
Companies operating in areas such as technology, artificial intelligence, semiconductors, and other innovative industries may fall into this category.
For example, Nvidia has attracted significant investor attention in recent years because of its role in artificial intelligence infrastructure.
However, rapid company growth does not automatically mean that its stock is attractively priced at any given time. The higher market expectations become, the more sharply a stock may react if the company delivers results below those expectations.
Large, Established Companies
Another category includes large, well-known companies with long operating histories, substantial revenues, and broad market presence.
Companies such as Apple, Microsoft, Alphabet, and Coca-Cola are examples of major U.S. corporations that investors may consider when evaluating the market.
However, a company’s size and reputation alone are not sufficient reasons to buy its stock. Valuation, financial condition, industry outlook, and the stock’s current price also matter.
Stocks Linked to Long-Term Trends
Some investors consider broader trends that could influence the economy over the coming years when building their portfolios.
Artificial intelligence, cybersecurity, energy infrastructure, healthcare technology, and semiconductors are among the areas that have attracted significant attention in recent years.
But there is an important distinction to keep in mind:
The growth of an industry does not necessarily mean that every company operating in that industry will grow.
An industry may have a strong long-term outlook, while some companies within it may still underperform because of competition, high debt, excessive valuations, or weaknesses in their business models.
What Should You Look for When Choosing a Stock?
Rather than focusing solely on a company’s name or its recent price growth, it is better to evaluate several key factors:
- Revenue and earnings growth
- Debt levels
- Cash flow
- Competitive advantages
- Industry conditions
- Growth prospects
- Valuation and financial ratios
- Management track record
- Business-specific risks
- The stock’s current price relative to its expected value
This type of analysis can turn an investment decision from an emotional choice into a more structured and analytical process.
Is It Better to Buy Individual Stocks or Invest in Indexes and ETFs?
The choice between individual stocks and ETFs depends on the investor’s knowledge, available time, financial objectives, and risk tolerance.
Buying individual stocks may provide the potential to outperform the broader market, but it also increases concentration risk because a larger portion of the portfolio may depend on the performance of a single company.
On the other hand, index ETFs can spread capital across a large number of companies. For example, ETFs that track the S&P 500 provide exposure to the performance of a broad group of large U.S. companies.
This does not guarantee returns or eliminate risk. The stock market can still experience significant periods of decline.
Therefore, a more important question than “Which stock is better?” is:
“What combination of assets is appropriate for my financial goals and risk tolerance?”
This brings us to one of the most important considerations for investors: wealth management, and when professional portfolio management can become valuable.
Wealth Management: When Investing Goes Beyond Choosing a Stock
As the value of an individual’s assets grows, managing wealth is no longer simply about answering the question, “Which stock should I buy?”
An individual may own real estate, bank deposits, stocks, investment funds, gold, or foreign-currency assets at the same time. In such circumstances, making decisions about each asset separately does not necessarily mean having a coherent overall financial strategy.
This is where the concept of wealth management becomes important.
Wealth management is a comprehensive approach to evaluating an individual’s financial position, objectives, assets, and risks, and then developing a strategy tailored to those circumstances.
What Does Wealth Management Actually Involve?
A wealth management plan can consider several areas together, including:
- Overall asset structure
- Liquidity needs
- Short- and long-term financial goals
- Risk tolerance
- Investment portfolio diversification
- International investments
- Retirement planning
- Ongoing portfolio management and review
- Potential tax implications and investment costs
The goal is not to place all of an individual’s capital in a particular market. Instead, the objective is to create a financial structure that aligns with the person’s circumstances and goals.
Who May Benefit From Professional Wealth Management?
Wealth management is not exclusively for extremely wealthy individuals.
For example, someone with a high income who has concentrated most of their capital in a single asset class may face greater concentration risk than someone with less capital but a more diversified portfolio.
Business owners, investors with multiple types of assets, and individuals seeking exposure to international markets may also benefit from a comprehensive wealth management strategy.
Ultimately, the need for such services depends not only on the amount of capital an individual has, but also on the complexity of their financial situation and their objectives.
How Is a Wealth Manager Different From a Trader?
These two roles should not be confused.
A trader generally focuses on buying and selling assets and attempting to benefit from price movements over shorter time periods.
Wealth management, by contrast, takes a broader view. It can consider an individual’s overall asset structure, financial objectives, risk profile, and long-term investment strategy.
As a result, a professionally managed portfolio may include stocks, ETFs, securities, cash, and other assets without requiring the investor to constantly buy and sell.
A Logical Process for Wealth Management
Professional wealth management generally begins with understanding an investor’s current financial position rather than immediately choosing a stock.
Step 1: Assess Your Financial Position
The first step is to determine what assets, liabilities, income sources, and financial obligations the individual has.
Step 2: Define Your Goals
The objective could be purchasing property, generating long-term income, preserving capital, funding retirement expenses, or growing wealth.
Step 3: Determine Your Risk Tolerance
Two people with the same amount of capital may have completely different capacities for taking risk. Therefore, portfolio allocation should not be determined solely by the amount of capital available.
Step 4: Build the Portfolio
Once the objectives and risk tolerance have been established, the investor can determine an appropriate asset mix, ranging from stocks and ETFs to other investment instruments.
Step 5: Review and Rebalance
An individual’s financial circumstances and market conditions do not remain constant. As a result, an investment portfolio may need to be reviewed and adjusted over time.
Ultimately, wealth management is not about finding a magic stock. It is about building a system for managing your overall wealth.
To understand this distinction more clearly, however, there is another important difference investors should know: How does long-term investing differ from short-term trading?
Investing or Trading: What Is the Difference?
One common mistake when entering the stock market is treating investing and trading as if they were the same thing.
Both involve buying and selling financial assets, but their objectives, time horizons, and decision-making processes can be very different.
What Is Investing?
Investing generally involves selecting assets with a medium- to long-term perspective, with the expectation that they will generate value or income over time.
For example, an investor may purchase shares of a company with the intention of holding them for several years while paying attention to the company’s business growth, profitability, and financial condition.
Alternatively, instead of investing in a single company, an investor may use diversified ETFs and funds to spread capital across a broader group of assets.
With this approach, daily market fluctuations are not necessarily sufficient reason to make frequent changes to the portfolio.
What Is Trading?
Trading generally focuses on attempting to benefit from price movements over shorter periods.
A trader may use technical analysis, economic news, company reports, or other factors to establish a buy or sell position and hold it for a shorter period.
In this approach, the speed of decision-making and risk management can be particularly important. The use of leverage in some markets can also significantly increase the risks associated with trading.
Is Trading Always a Bad Idea?
No.
Trading is a financial activity that differs from long-term investing and can be a viable trading strategy for individuals with the appropriate knowledge, experience, time, and risk tolerance.
The problem arises when someone enters the market without understanding the risks, simply hoping to make quick profits.
This is particularly important in leveraged trading, where a relatively small movement in an asset’s price can have a significant impact on a trader’s capital.
For this reason, potential returns should never be considered without also considering the potential risks.
Why Is Long-Term Investing Simpler for Many People?
Managing a long-term investment strategy generally does not require the same level of constant price monitoring as short-term trading.
For example, an investor who chooses a diversified ETF with a multi-year investment horizon may focus more on portfolio allocation, costs, economic conditions, and financial objectives than on market fluctuations over the course of a few hours.
However, a long-term approach does not guarantee returns. The stock market can experience prolonged periods of declines or volatility, and investors need to be able to withstand such periods.
One Common Mistake: Chasing Quick Profits
When markets rise for a period of time, it can create the impression that making money from investing is easy.
But a stock’s or market’s past performance does not guarantee future results.
Successful investing is more like a process than a single decision:
Financial goal → Investment strategy → Portfolio construction → Risk management → Periodic review
If these steps are ignored, even choosing a very strong company does not necessarily lead to the desired outcome.
Which Investment Strategy Is Right for You?
The answer depends on your individual circumstances.
If your goal is to build wealth over the long term, a diversified and disciplined investment approach may be more compatible with your financial objectives.
If you are interested in trading, you should first study capital management, position sizing, leverage, trading costs, and the potential for losses before entering the market.
In either case, the most important point is to understand why you are buying an asset and under what circumstances you would change your decision.
But investing is not only about choosing an asset. There is another, even more important question: How can you increase your capacity to invest over time?
Investing Is Not the Only Thing That Matters; Your Income Needs to Grow Too
Focusing on choosing a stock, fund, or market can sometimes cause investors to overlook an important point:
If your investable income does not increase, your capacity to build wealth will remain limited.
Suppose two people both invest a portion of their income every year. If one of them manages to increase their income over several years while maintaining the same savings rate, they will have more capital available to invest.
This is why building wealth generally requires two parallel paths:
Increasing income + Consistent investing
Higher Income Creates More Opportunities to Invest
Income can increase in many ways, from developing specialized skills and advancing professionally to starting a business or creating new sources of income.
But increasing income alone is not enough.
If all additional income is spent on a higher standard of living, the amount available for investment may change very little despite the increase in earnings.
This is where the difference between higher income and greater wealth becomes clear.
A High Income Does Not Necessarily Mean High Wealth
Someone may earn a substantial income, but if a large portion of it is spent on consumption and little is invested for the future, they may not necessarily build significant wealth.
By contrast, someone with an average income who consistently saves, controls expenses, and invests for the long term can gradually increase their assets.
Therefore, financial planning should consider three questions together:
- How much income do we generate?
- How much of it do we retain?
- How do we put the capital we retain to work?
Separate Investing From Your Income
One important principle of financial management is not to treat all monthly income as money available for current expenses.
A portion of income can be allocated to essential expenses, another portion to short-term goals, and another portion to long-term investments.
The appropriate allocation depends on factors such as income, financial obligations, age, objectives, and individual circumstances. There is no single fixed percentage that applies to everyone.
Don’t Underestimate the Power of Time
When money is invested regularly and investment returns are reinvested, the effect of compound growth can become significant over the long term.
For example, regular monthly investing may not produce a dramatic change during the first few years. Over time, however, both new contributions and accumulated returns can contribute to the growth of invested capital.
Of course, compounding only works in an investor’s favor when returns are positive and achievable, and there is no guarantee of a particular level of return.
Therefore, the goal should not be to find the fastest way to become wealthy.
The goal is to generate income, preserve a portion of it, and put that capital to work through a logical investment plan that is appropriate for the level of risk involved.
This brings us to one of the most important tools available in the investment market: investment funds—an option that can give people who do not want to select individual stocks themselves access to a more diversified investment approach.
Investment Funds: A Way to Build a More Diversified Portfolio
So far, we have discussed buying shares in different companies and the difference between investing and trading. But investors do not always have to select individual stocks themselves.
One of the tools that can make this process simpler is an investment fund.
An investment fund pools capital from multiple investors and invests it across a range of assets according to a defined strategy. This allows investors to gain exposure to a collection of assets through a single fund rather than selecting and managing a large number of investments individually.
How Do You Choose the Right Investment Fund?
There is no single fund that is the best choice for everyone.
The right fund should align with several key factors:
- Investment objective
- Investment horizon
- Risk tolerance
- Types of assets held by the fund
- Fees and expenses
- Historical performance
- Level of diversification
- Fund manager’s investment strategy
For example, someone looking to preserve liquidity and limit volatility may consider lower-risk investment vehicles, while an investor with a longer time horizon and greater risk tolerance may consider funds with greater exposure to equities.
Equity Funds
Equity funds invest a significant portion of their capital in company stocks.
These funds can give investors exposure to a range of companies at the same time, helping reduce the risk of concentrating the portfolio in a single company.
However, reducing concentration risk does not eliminate market risk. If the stock market declines, the value of an equity fund can also fall.
Index Funds and ETFs
One of the most widely recognized approaches to investing in the U.S. market involves funds that track the performance of a market index.
For example, there are ETFs designed to track the performance of the S&P 500.
The main advantage of this approach is that instead of selecting a single company, investors gain exposure to the performance of a broad group of large companies.
However, an index can also decline, meaning that investing in an index ETF still involves stock-market risk.
Gold-Related Funds and Other Asset Classes
Not all investment funds invest in stocks.
Some funds and ETFs provide exposure to assets such as gold, bonds, or other asset classes.
These instruments can play a role in certain diversification strategies. However, they should also be selected based on the investor’s objectives and the overall structure of the portfolio.
Is One Fund Enough?
Not necessarily.
Holding a diversified fund can help prevent excessive concentration in a single company, but a portfolio may still face significant risk if it is heavily concentrated in one market, industry, or asset class.
For this reason, portfolio construction should focus on the composition of the entire investment portfolio rather than the performance of a single fund. U.S. SEC: asset allocation.
Ultimately, the choice between individual stocks, ETFs, investment funds, and other assets should be part of a broader financial plan.
The goal of investing is not simply to find the asset with the highest potential growth. The goal is to build a portfolio that aligns with your financial objectives and risk tolerance.
Conclusion: Successful Investing Does Not Start With Choosing a Single Stock
The U.S. stock market provides access to a broad range of companies, industries, and investment vehicles. However, entering this market alone does not guarantee financial success.
Before making any investment, you should first determine why you are investing, how long you can keep your capital invested, and how much volatility and potential loss you are able to tolerate.
Only then can you make a more informed choice among options such as individual stocks, ETFs, investment funds, and other investment vehicles.
If you plan to invest directly, you should choose a brokerage that is able to provide services to you under the applicable requirements. Before opening an account, review its KYC requirements, fees, available trading instruments, and the rules governing the account.
On the other hand, if you prefer to delegate portfolio construction and management to professionals, financial advisory or professional wealth management services may be options worth considering.
What to Check Before Making Your First Investment
- Define your financial objective.
- Determine your investment horizon.
- Understand your risk tolerance.
- Research the asset you are considering buying.
- Understand the differences between stocks, ETFs, investment funds, and CFDs.
- Avoid concentrating all of your capital in a single stock or market.
- Review all fees and expenses.
- Check the legal and tax requirements associated with international investing.
- Avoid emotional decisions and constant attempts to time the market.
- If your financial circumstances are complex, you can seek guidance from our advisors and specialists.
Ultimately, investing in the U.S. market is not a race to find the fastest possible return.
Building wealth is typically the result of a combination of income, saving, consistent investing, diversification, risk management, and time.
So instead of asking only, “Which stock should I buy?”, ask a more important question:
“How can I build an investment plan that I can stick to for years?”
The answer to that question can be the starting point for a more logical and sustainable long-term investment journey.


